Emerging financial markets are often shaped by economic uncertainty, political developments and global financial shocks, making accurate volatility forecasting essential for informed investment decisions. Daniel Sila, a student at Murang’a University, explores this challenge in his completed research paper, Modelling Share Market Volatility in Emerging Markets Using GARCH Modelling.
Using data from the MSCI Emerging Markets Index covering 2015–2025, the study examines market return patterns and applies several Generalised Autoregressive Conditional Heteroskedasticity (GARCH) models to understand and forecast volatility. The analysis identifies persistent volatility clustering and asymmetric market responses, where negative shocks can trigger stronger volatility than positive shocks of comparable magnitude. Among the models evaluated, EGARCH delivered the best overall fit, demonstrating its value in capturing these asymmetric market movements.
The research offers valuable insights for investors, investment firms, portfolio managers, financial institutions and research organisations seeking to strengthen financial risk assessment and investment strategies. By using historical market data to estimate future volatility, the study can support more informed portfolio optimisation and risk management decisions. Its interdisciplinary approach combines established statistical and econometric principles with financial market analysis to address the complexities of emerging economies.
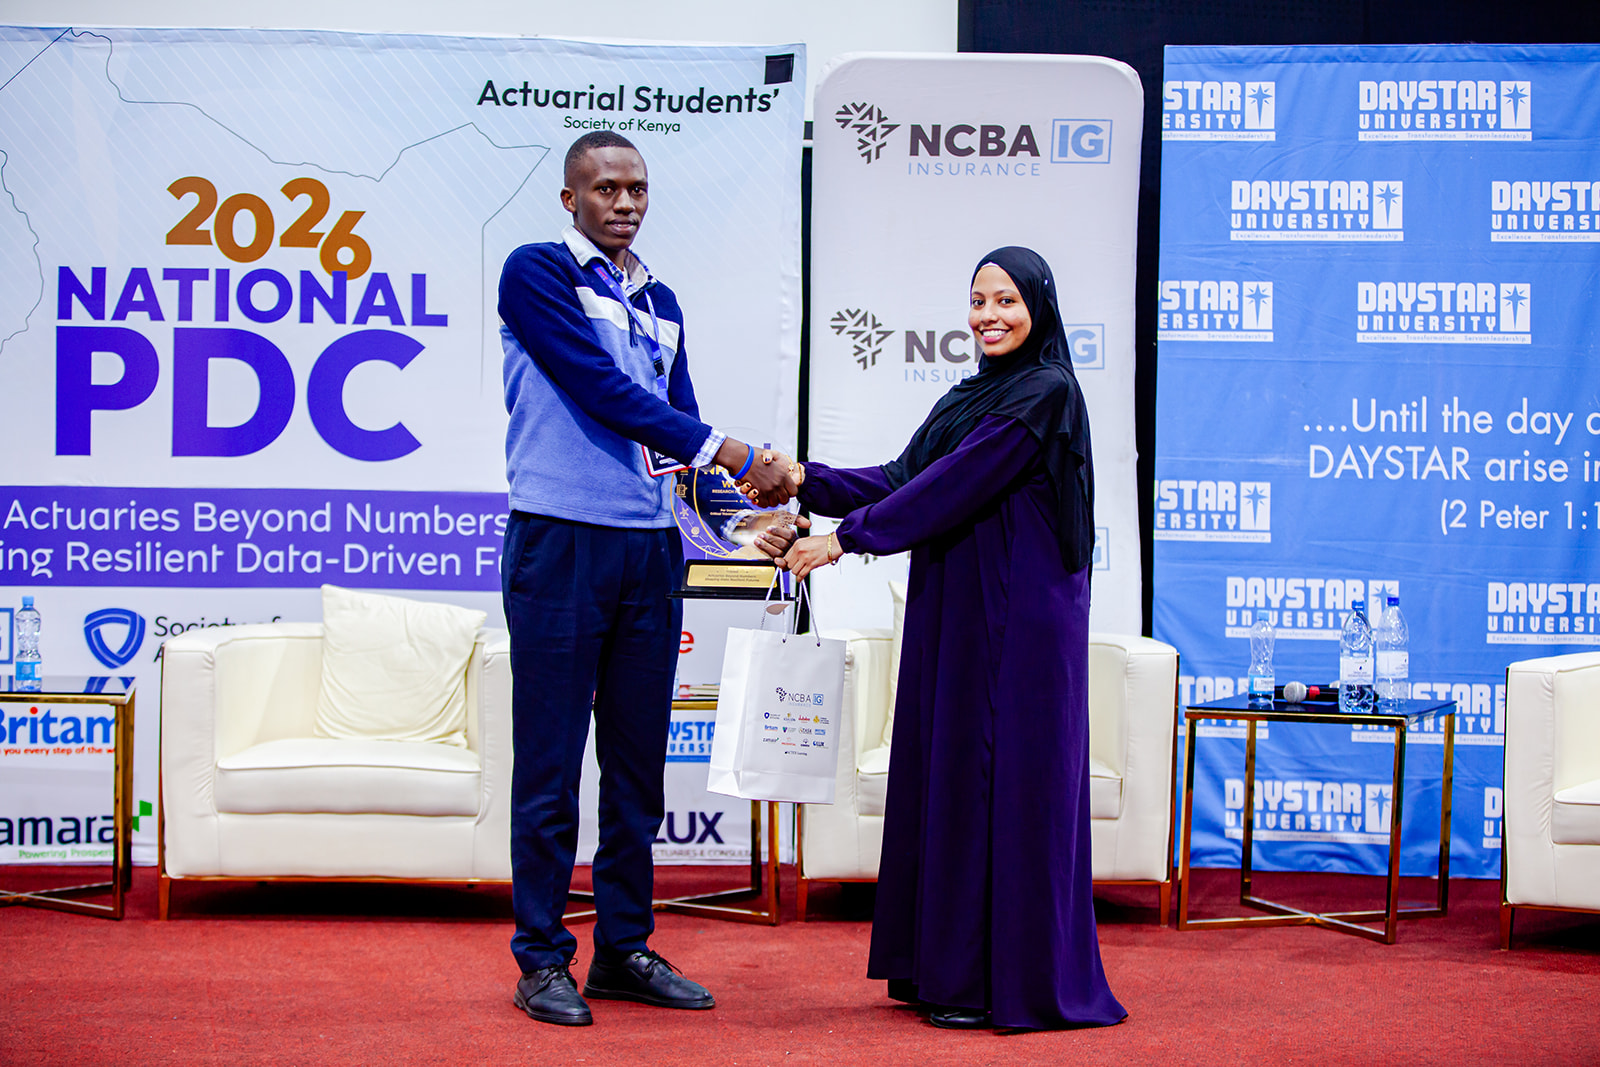
Daniel’s work achieved national recognition, emerging as the Best Research Paper in the 2026 National Product Development Competition held at Daystar University. This achievement highlights the role of actuarial and quantitative research in addressing real-world financial challenges and demonstrates how emerging professionals can contribute to data-driven investment decision-making.
As the research moves beyond completion, opportunities remain to explore its practical application through collaboration with investment firms, financial institutions, researchers and other industry stakeholders. The findings also point towards future research involving macroeconomic indicators, multivariate GARCH models, volatility spillovers and machine-learning techniques to further enhance forecasting capabilities.
Through its Product Development Competition, the Actuarial Students Society of Kenya (ASSK) continues to spotlight innovative research and encourage the next generation of actuaries to translate mathematical knowledge into practical solutions for industry and society.
Meet the Researcher
Daniel Sila – Murang’a University
Email: danielsilah72@gmail.com
LinkedIn: Connect with Daniel Sila
Interested in collaboration or partnership? Contact ASSK to explore opportunities to support the application and further development of innovative actuarial research.
This product was presented in this year’s (2026) National PDC held at Daystar University