For millions of Kenyans whose incomes arrive transaction by transaction rather than through a fixed monthly salary, this simple question represents a much bigger financial challenge. It is the challenge that inspired PesaPilot-AutoSaving, an innovative financial collection mechanism designed to automatically connect everyday mobile-money transactions with savings and insurance.PesaPilot-AutoSaving is built around a simple idea: make saving and insurance collection part of the payment itself.
Developed by Emmanuel David Odhiambo Omenya from Meru University of Science and Technology, PesaPilot-AutoSaving is designed for Kenya’s informal economy, where millions of workers earn, spend and receive money through mobile payments but often lack financial mechanisms adapted to the realities of irregular income. Instead of asking users to remember to transfer money into a savings account or initiate an insurance premium payment at the end of the month, PesaPilot seeks to make these actions automatic. Once a user configures a savings percentage, every eligible M-Pesa payment can trigger an automatic allocation toward savings, while a portion of accumulated savings can then be swept toward an active insurance premium, reducing reliance on memory and manual payments to maintain coverage.
The ambition is therefore not simply to introduce another savings or insurance product into an already crowded financial market. PesaPilot seeks to change the collection mechanism itself.
This distinction matters.
Kenya’s informal economy represents a significant part of the country’s workforce, yet many financial products continue to be structured around assumptions that work better for people with predictable salaries and fixed monthly incomes. For an informal worker, however, income may arrive through dozens of small transactions rather than one monthly salary. A financial product that expects the user to set aside money manually at a particular time may therefore be fighting against the very circumstances of the person it is designed to serve.PesaPilot attempts to reverse that relationship. Instead of asking the user to change their financial behaviour, the mechanism is designed to work around the behaviour that already exists.
Imagine a trader paying a supplier, a mechanic receiving a customer payment, a salon operator making a business transaction or a small business owner paying for stock. Under the proposed PesaPilot mechanism, a configured portion can automatically be directed toward savings as part of the transaction process. Over time, those small allocations can accumulate without requiring the user to repeatedly make a separate savings decision.The same principle extends to insurance.A portion of accumulated savings can be automatically directed toward an active insurance premium, creating a continuous collection mechanism intended to reduce the likelihood of coverage lapsing simply because a payment was forgotten.
In essence, one financial moment can serve multiple purposes: completing the transaction, building savings and supporting insurance coverage.
That is the core proposition of PesaPilot-AutoSaving.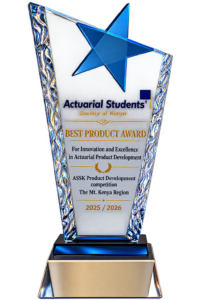
Turning Everyday Transactions Into Financial Intelligence
The product’s ambition extends beyond automated savings.Every transaction can potentially generate structured information about financial behaviour. Over time, the platform could build a behavioural financial profile based on signals such as transaction frequency, savings consistency, withdrawal patterns, goal completion, balance trajectory and premium-payment regularity.
This creates another layer of value.For a large population of informal workers who may have limited formal financial histories, behavioural data could potentially provide new ways of understanding financial resilience. Subject to appropriate consent, privacy protections and regulatory requirements, such information could support the development of insurance pricing models based on observed financial behaviour, alternative credit assessment and portfolio-level analysis of financial resilience.
For actuaries, this is particularly significant.The informal economy is not simply a market waiting for financial products. It is also a population whose financial behaviour can generate new actuarial questions. How consistent is an individual’s income flow? How resilient are their savings? How frequently do they withdraw accumulated funds? How regularly can they maintain an insurance contribution? How does financial behaviour change during periods of economic stress?
These are questions that can transform raw transaction data into risk intelligence.PesaPilot therefore sits at an interesting intersection of mobile money, savings, insurance, actuarial science and financial data.
Designed Around Kenya’s Informal Economy
The initial opportunity is substantial.Kenya’s informal economy encompasses traders, mechanics, salon operators, market vendors, smallholder farmers, service providers and thousands of small-business owners whose financial lives increasingly depend on mobile money.PesaPilot’s proposed market strategy begins with smartphone-enabled users before expanding toward a broader mobile-money population through deeper transaction-level integration.
The long-term vision is particularly ambitious: a mechanism that could operate across different M-Pesa payment channels, including users who rely on USSD and agent-based transactions rather than smartphones.If successfully implemented, the model could extend beyond Kenya as well. The underlying problem – irregular income meeting financial products designed around fixed payment schedules – is not unique to one country. Similar challenges exist across other mobile-money and emerging-market ecosystems.This gives PesaPilot the potential to become more than a Kenyan financial innovation. It presents a model that could eventually be adapted to other markets where informal employment, mobile money and limited access to formal financial products intersect.
A New Way of Thinking About Insurance
Perhaps the most compelling aspect of PesaPilot is its potential to challenge how insurance is distributed to informal workers.Insurance penetration remains relatively low in Kenya, while traditional distribution channels often depend on employers, banks, agents or structured payment arrangements. For someone earning an irregular income, a fixed monthly premium can create friction even when the actual cost of the product is affordable.PesaPilot approaches the problem from a different direction.Rather than asking, “How do we convince an informal worker to remember to pay for insurance every month?”, it asks:
“How can the collection mechanism become part of the way that person already moves money?”
That shift- from product design to collection design – is at the heart of the innovation.It could also create opportunities for insurers to reach previously underserved segments through digital distribution while gaining access to richer behavioural information that may support future actuarial analysis and product development.
The Actuarial Opportunity
For the actuarial profession, PesaPilot illustrates how technology can expand the role of the actuary from traditional risk calculation into product architecture and financial innovation.The mechanism generates questions around risk selection, behavioural modelling, affordability, persistence, lapse risk, customer segmentation, insurance pricing and financial resilience.The actuarial opportunity is not simply to calculate a premium after the product has been designed.It is to help design the system through which the premium is collected, understand the behaviour that drives persistence, model the risks emerging from transaction patterns and ultimately use data to create better financial products.This is the kind of thinking that the next generation of actuaries will increasingly need.The future actuary may not only price risk. They may help design the infrastructure through which millions of people manage it.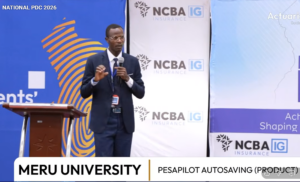
From Prototype to Platform
PesaPilot-AutoSaving is still at the product-development stage, making the journey ahead as important as the idea itself.The proposed architecture envisions an initial model built around mobile-money APIs, followed by a broader transaction-event integration that could potentially extend automatic saving across multiple M-Pesa payment channels. The long-term vision is to make the experience as seamless as possible: users continue paying the way they already do, while the savings mechanism operates in the background according to their chosen configuration.The model also envisions integration with savings and investment products, including money-market solutions, alongside insurance premium collection.If successfully validated and implemented, this could transform PesaPilot from a savings mechanism into a broader financial infrastructure layer for the informal economy.
That is where the commercial opportunity becomes particularly interesting.Revenue could potentially be generated through financial-service fees, investment-product partnerships, insurance distribution, credit-scoring services and institutional data analytics, subject to the necessary regulatory approvals, commercial agreements and responsible data-use frameworks.The result is a model in which the consumer-facing product solves a practical financial problem while the underlying infrastructure creates opportunities for multiple financial institutions to participate in the ecosystem.
An Opportunity for Investors and Partners
PesaPilot-AutoSaving presents a proposition that extends beyond another consumer-finance application.Its larger opportunity lies in the infrastructure underneath the user experience: connecting everyday mobile-money activity with savings, insurance and financial intelligence.For insurers, it could provide a new distribution mechanism into the informal economy.For lenders, it could contribute to alternative approaches to assessing customers with limited formal credit histories.For financial institutions, it could create new channels for savings and investment products.For technology partners, it presents opportunities around payments infrastructure, APIs, data systems and financial automation.For researchers and actuaries, it creates a new environment for studying financial behaviour and resilience among informal workers.And for investors, it offers an opportunity to engage with an emerging financial-infrastructure concept addressing a large and underserved market.
The ambition is therefore much larger than simply helping people save a little more.It is about building financial systems that understand how people actually earn, spend, save and protect themselves.
Innovation With Responsibility
As with any platform operating within financial services, payments, insurance and behavioural data, responsible innovation must remain central.Any real-world implementation would require appropriate regulatory approvals, consumer protection measures, data privacy and security controls, transparent consent mechanisms and robust governance around the use of financial and behavioural information.The value of the data must never come at the expense of the people generating it.The objective should be to use technology and actuarial insight to expand financial inclusion while maintaining trust, transparency and responsible data practices.
Beyond Numbers, Into Infrastructure
PesaPilot-AutoSaving captures an important idea about the future of actuarial innovation.Some of the most powerful financial products may not be the ones that ask consumers to do more. They may be the ones that quietly remove friction from behaviours people already want to adopt.Saving should not have to depend on remembering.Insurance should not have to lapse simply because a payment was missed.And access to financial services should not depend entirely on having a fixed monthly salary.
By connecting everyday transactions with savings, insurance and behavioural risk intelligence, PesaPilot-AutoSaving offers a glimpse of what financial inclusion could look like when mobile money, actuarial science and technology are designed around the realities of the informal economy.It is also a reminder of what product development can unlock.A student idea can become a prototype. A prototype can become a partnership. A partnership can become a platform. And a platform, with the right validation, investment and execution, can potentially become infrastructure capable of serving millions.That is the opportunity presented by innovations emerging from actuarial product development.
Not just calculating the future – but building the financial systems that help people prepare for it.
Taking PesaPilot Further
PesaPilot-AutoSaving is an emerging innovation with the potential to evolve through technical development, actuarial validation, regulatory engagement and strategic partnerships.The Actuarial Students’ Society of Kenya (ASSK) welcomes engagement from insurers, financial institutions, technology companies, investors, researchers and other organisations interested in supporting, validating, partnering on or exploring the commercial potential of student-led actuarial innovations.For partnership and collaboration opportunities around PesaPilot-AutoSaving and other innovations emerging from the Product Development Competition, reach out to ASSK.
The future of actuarial science is not only about understanding how money moves.
It is about reimagining how financial systems can work for everyone.
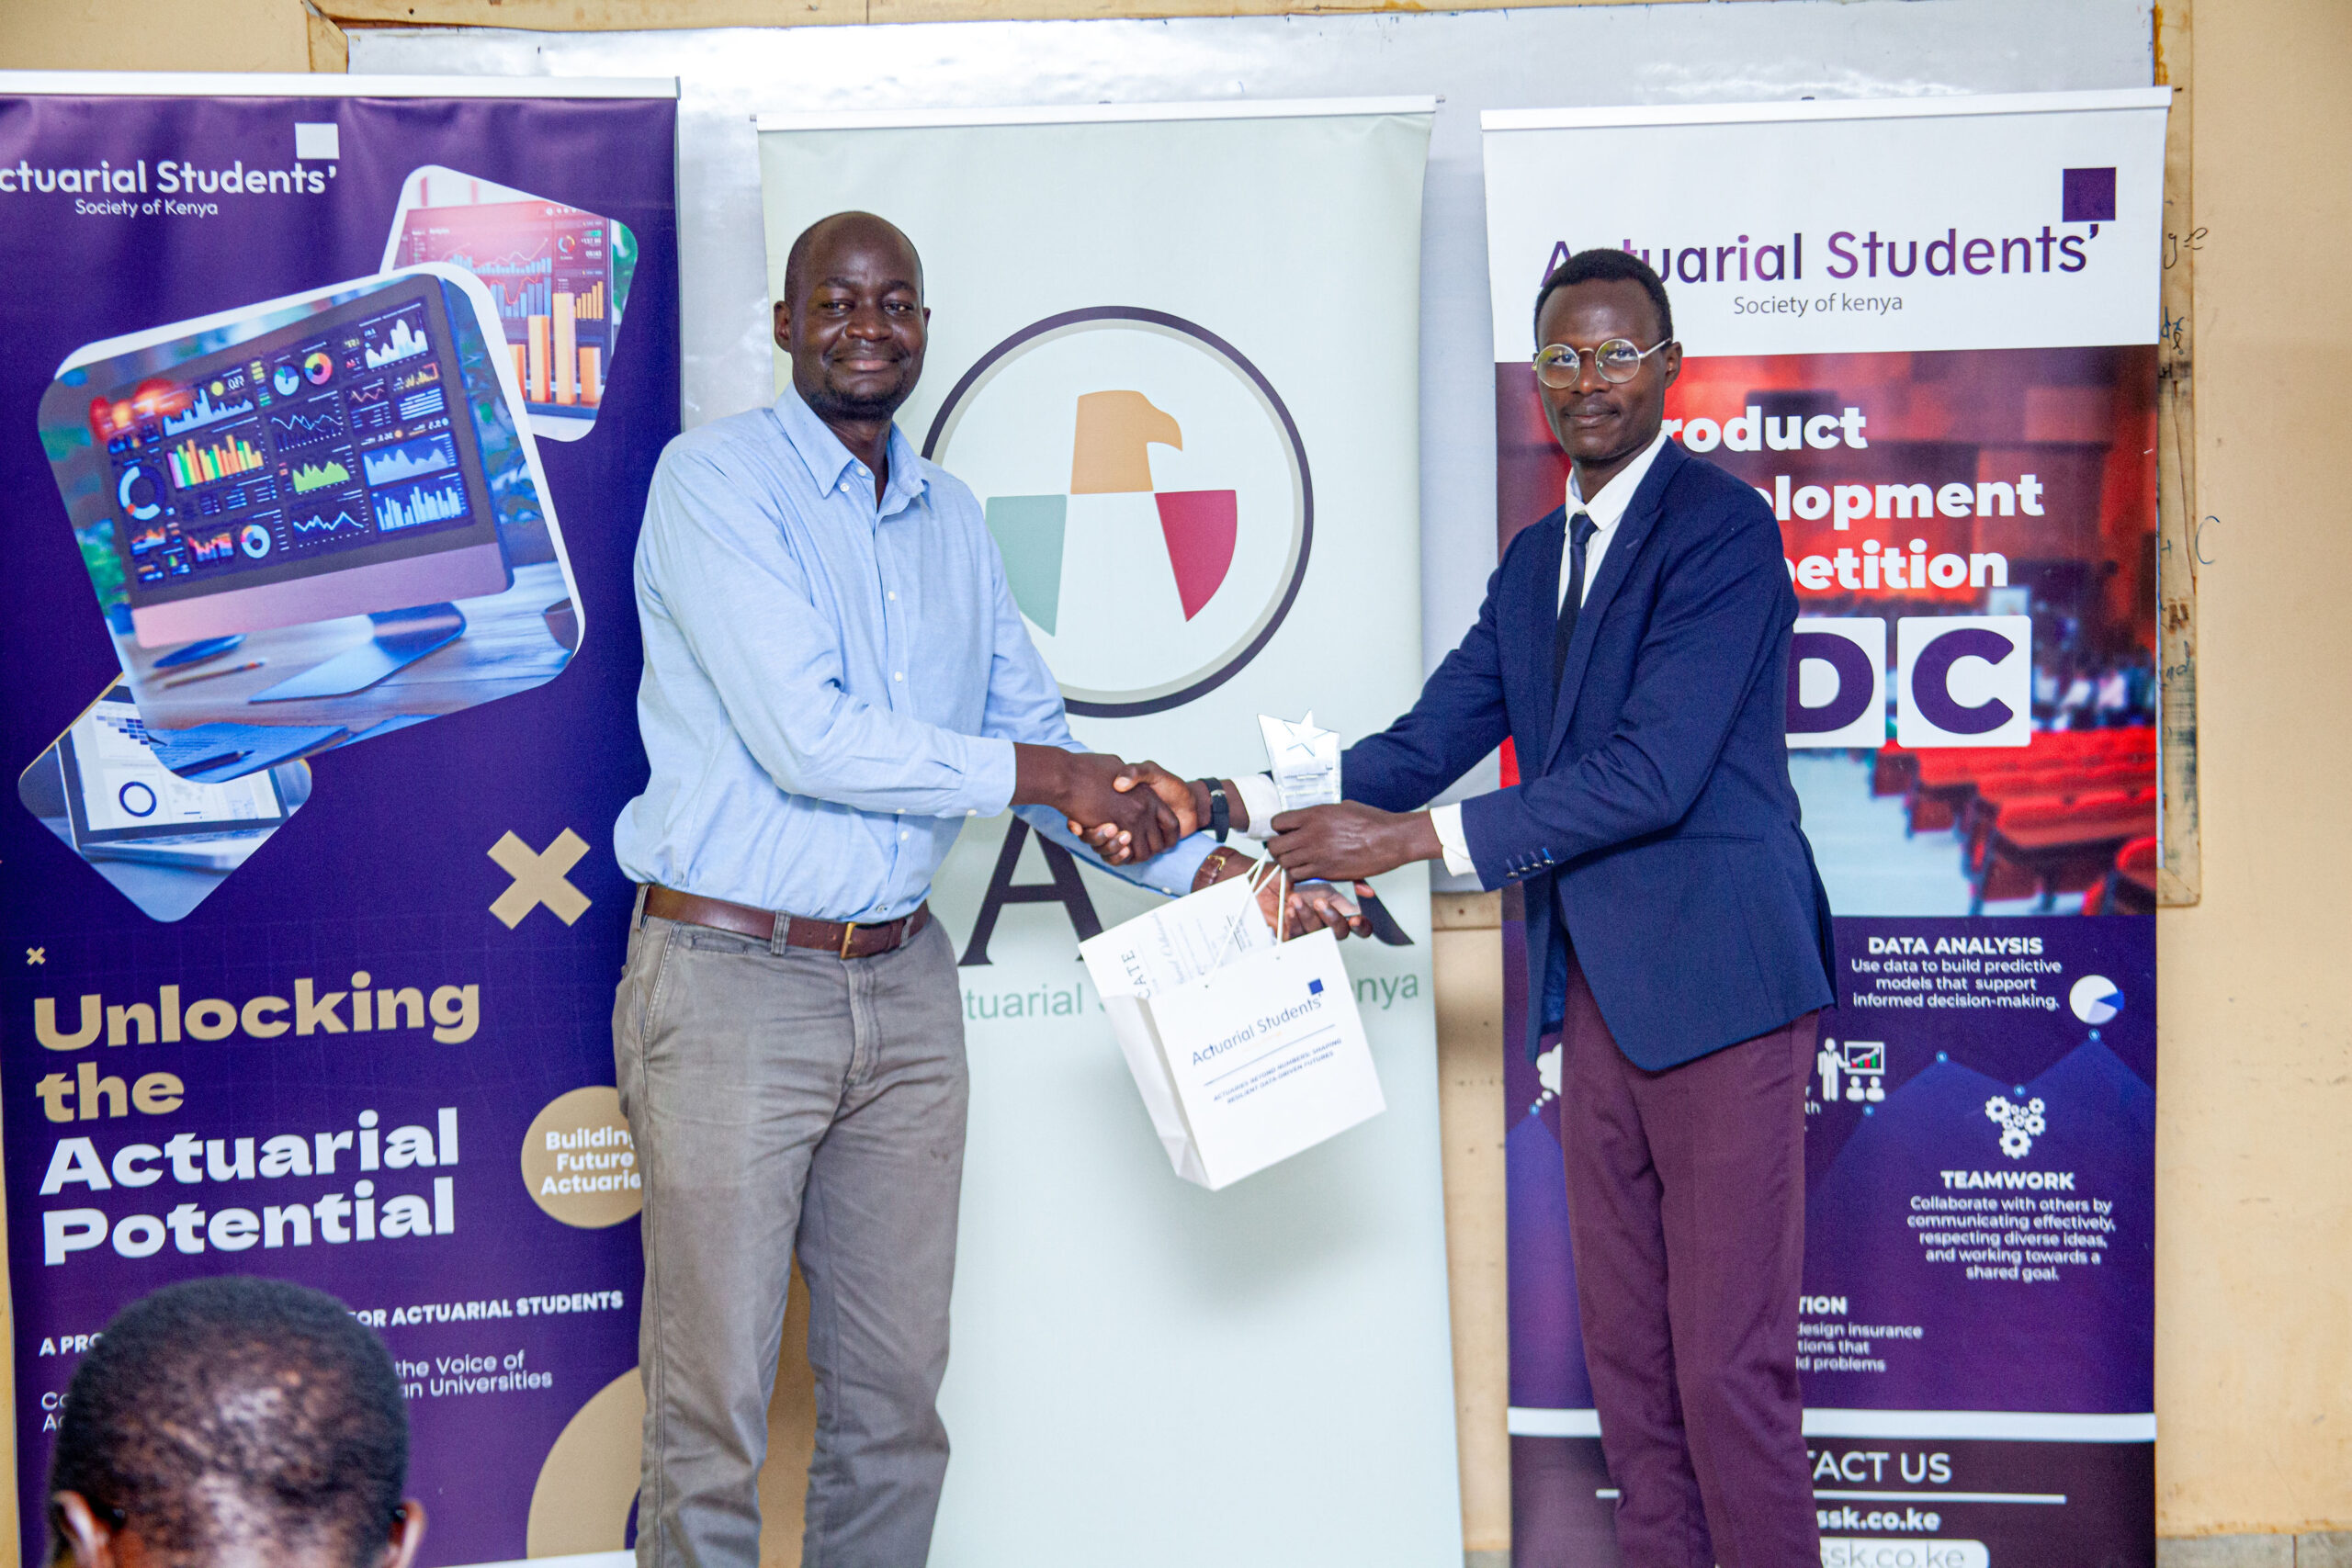
This product was presented in this year’s (2026) National PDC held at Daystar University